Standard payment
$0monthly savings
Starting point
7.37% assumed note rate
APR not provided
$2,867subtotal per month
$2,867subtotal per month
$2,867subtotal per month
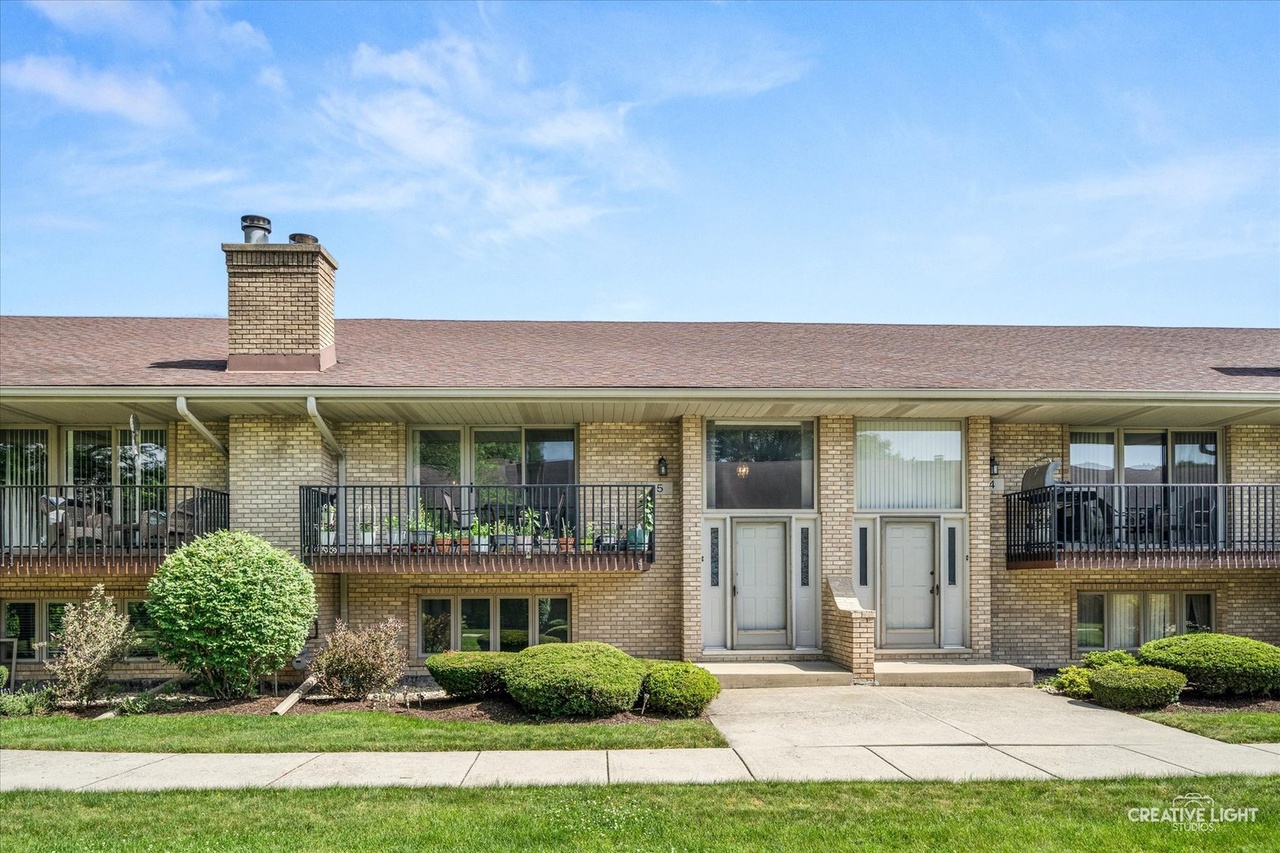
EXPLORE WHAT SELLER HELP COULD DO
The asking price is only part of the conversation. See how a negotiated seller credit could lower your early payments, help buy a lower fixed rate, or help with closing costs.
Darien, IL 60561
$350,000
2 bedrooms • 2.5 baths • 1,820 sq ft
See what seller help could changeDownload payment PDF and consumer handoutCompare options without entering your contact information.
Planning example. Seller willingness to provide a credit has not been confirmed.
START WITH WHAT MATTERS TO YOU
Choose a goal. We’ll show you what to compare and the tradeoff to watch.
These are potential uses of one negotiated credit. They are not three separate incentives. Seller agreement, qualification, program limits and lender approval apply.
ESTIMATED PAYMENT COMPARISON
A lower price and a seller credit solve different problems. Compare the monthly difference, then check what happens later.
Planning estimates, not lender quotes. Rates are assumptions based on the dated MND benchmark. APR and buydown costs have not been supplied. Seller funding and loan eligibility are unconfirmed.
With 10% down, the estimated 2/1 subsidy is $7,464. A $10,000 seller credit would leave approximately $2,536 for other allowable closing costs, subject to actual costs, program limits and lender approval. This is not cash back. Separate program fees, if any, would reduce the remainder. The permanent rate reduction requires an actual quote; its cost is not assumed to be $10,000.
Hypothetical incentive for comparison. Seller agreement has not been confirmed.
1. Choose your down payment
10% down · $315,000 starting loan · $417.17 monthly reported taxes · $275 monthly HOA · Insurance and PMI excluded · Rate reference: October 16, 2026
Opens your 6 page marketing packet with payments, education and next steps. Use the PDF viewer’s print or save control. The packet matches your selected down payment.
2. Compare the savings and all payment stages
monthly savings
Starting point
7.37% assumed note rate
APR not provided
less per month
For the loan term
7.37% assumed note rate
APR not provided
less per month
Year 1 only
7.37% assumed note rate
APR not provided
less per month
For the loan term
6.87% assumed note rate
APR not provided
Year 1: months 1 to 12. Year 2: months 13 to 24. Year 3 onward: months 25 to 360. All examples use a 30 year fixed conventional loan. Savings compare principal and interest. Figures are rounded separately. Property expenses may change. The $10,000 price reduction is hypothetical. Options do not assume equal seller costs. Taxes use reported 2024 history, not a new tax quote. Condo eligibility requires lender review.
A 2/1 buydown provides temporary room in your budget. Plan for the full payment in Year 3 without depending on a refinance.
TAKE THE NUMBERS WITH YOU
Your PDFs match the selected 10% down example.
Opens the finished PDF in a new tab. Print all 6 pages or save the file. On phones, use the PDF viewer’s share or save options.
THE PROPERTY
A townhome-style condo with two bedrooms, a balcony, a lower-level family room and a two-car attached garage. Property features are reported by the listing and should be confirmed with the agent.
UNDERSTAND THE TRADEOFF
A negotiated price reduction can lower the amount you borrow. Compare the resulting payment and remaining balance with your other options.
A funded account pays part of the scheduled payment. Your share rises in Year 2 and again in Year 3. Your note rate and loan balance follow the standard schedule.
A lower fixed rate may require an upfront cost. Request current pricing and compare that cost with the expected savings over the time you keep the loan.
The old loan is paid off and its future savings end. A lower remaining balance still matters. Unused temporary buydown funds follow the written agreement. A cash refund is not guaranteed. Compare any new loan costs, payment and payoff date before refinancing.
It is when savings recover an extra upfront cost. Eric can calculate it once the actual rate reduction and cost are quoted. Comparing monthly savings alone differs from also considering the remaining loan balance. A line crossing on a gross savings chart is not a fee adjusted break even.
Do not treat a seller credit as your down payment. Eligible uses and contribution limits depend on the loan, occupancy, value and other contributions. Eric can help review the proposed credit before an offer is structured.
MEET YOUR FINANCING TEAM
Get to know the Eric Hamilton Team and how we help buyers understand their options.
LET’S MAKE IT PERSONAL
Tell Eric which option caught your attention. We’ll help you compare a complete payment, the cost of the incentive, and what fits your timeline.
Want a personal review? Leave your name and phone for Eric to follow up.